
Wells: Solve for the payment, not the rate
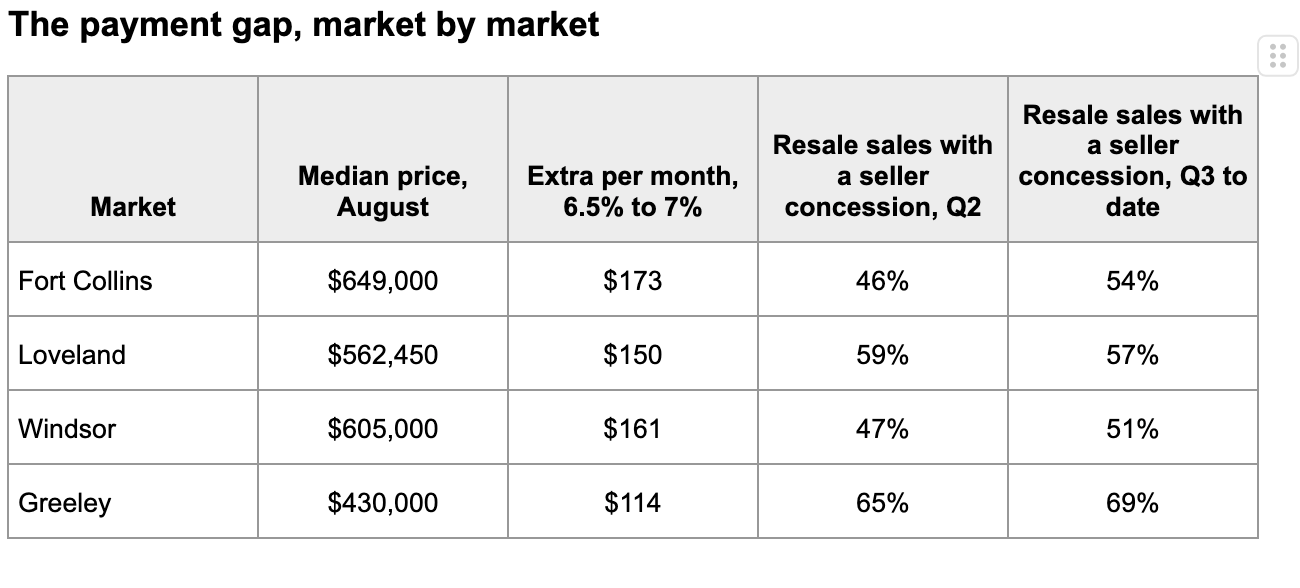
Picture two buyers who will write the exact same mortgage check every month for the next 30 years. One buys a home for $600,000 at a 6.25% rate. The other buys the same home for about $555,000 at 7%. Same house. Same payment. Very different headline.
Rates are 7%. I hear it constantly, usually followed by some version of “Why would anyone buy right now?” It’s a fair reaction. Freddie Mac’s 30-year fixed rate reached 7.03% in late September, its highest level in more than a year and a half.
But here is what that headline leaves out. This spring, rates were near 6.25%, and they hovered around 6.5% into July. Buyers across Northern Colorado were buying homes at those rates. If the payment worked for you then, the question isn’t when that rate comes back. It’s how to get back to that payment. Don’t let the 7% headline do your thinking for you.
Bridging the gap
Rising rates didn’t change the house. They changed the payment, and that difference is a gap you can negotiate.
A simple rule of thumb helps: Every quarter point of rate is worth about 2.5% of the price. For a median-priced home in Fort Collins, moving from 6.5% to 7% adds about $170 a month. Closing that gap with price alone would take roughly a 5% discount. That’s a big ask of any seller. Fortunately, price is only one of the tools on the table.
Sellers are ready to talk
This summer was not a bust. Homes sold at a healthy pace. But more homes came to market than sold, and Northern Colorado’s four primary markets entered fall with about 55% more homes for sale than in January. That’s a lot of sellers still waiting for the right buyer.
They’re also showing they’re willing to negotiate, most often through seller concessions, money the seller puts toward the buyer’s closing costs or rate. Builders have leaned on them hardest, with roughly three in four new-construction sales in our four primary markets including one. But resale sellers are getting competitive too, especially where they’re up against new-construction neighborhoods, and as rates climbed this summer, more of them came to the table.
In the second quarter, 53% of resale home sales in Fort Collins, Loveland, Windsor and Greeley included a concession. Through late September, the third quarter is running at 57%. In Fort Collins, the share jumped from under half to more than half.
The opportunity on concessions is growing, not shrinking.
That’s where the gap gets bridged. It rarely takes price alone. A modest price reduction, paired with seller money toward buying down the buyer’s rate or covering closing costs, can bring the monthly payment close to where it would have been at 6.5%. The seller protects more of the price. The buyer gets back a payment that works. Both sides get to the closing table.
And remember: you can refinance a rate. You can’t refinance what you paid. If rates ease, you have options. If they don’t, you still own a home you bought for less.
Sellers, this cuts both ways
A $600,000 home priced as if rates were still 6.25% is asking today’s buyer to pay about $238 more every month. The sellers who help solve for the buyer’s payment are the ones best positioned to sell this fall.
The buyers who come out ahead in this market won’t be the ones waiting for a better headline. They’ll be the ones who know the payment that works for them, lean on a trusted advisor to negotiate the right mix of price and concessions, and find a seller ready to meet them there.
Picture two buyers who will write the exact same mortgage check every month for the next 30 years. One buys a home for $600,000 at a 6.25% rate. The other buys the same home for about $555,000 at 7%. Same house. Same payment. Very different headline.
Related Posts
-
Colorado’s adjusted unemployment rate increased two-tenths of a percentage point in March to 3.7%.
-
Colorado’s seasonally adjusted unemployment rate ticked up from 4% in August to 4.1% last month,…
-
DENVER — Fewer Coloradans are uninsured than ever before, according to a new report from…
-
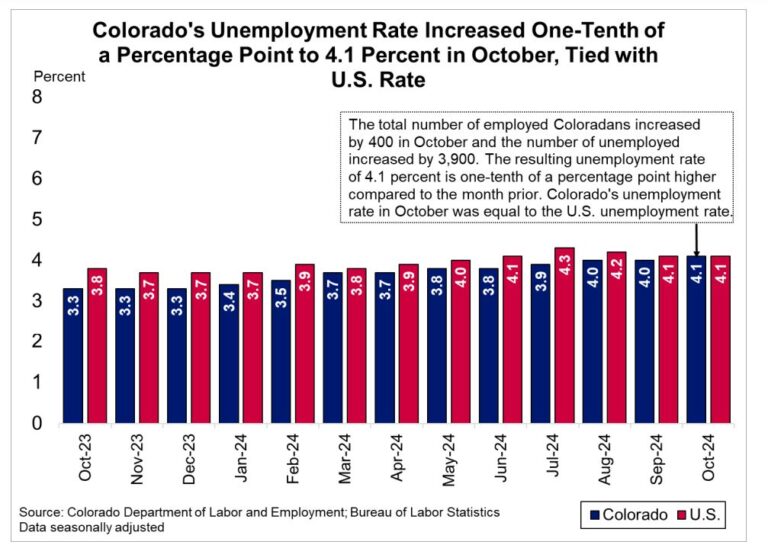
Colorado’s seasonally adjusted unemployment rate rose one-tenth of a percentage point between September and October…
